Adobe: $4.62 or $6.13 EPS? Read the Reconciliation
Adobe: $4.62 or $6.13 EPS? Read the Reconciliation
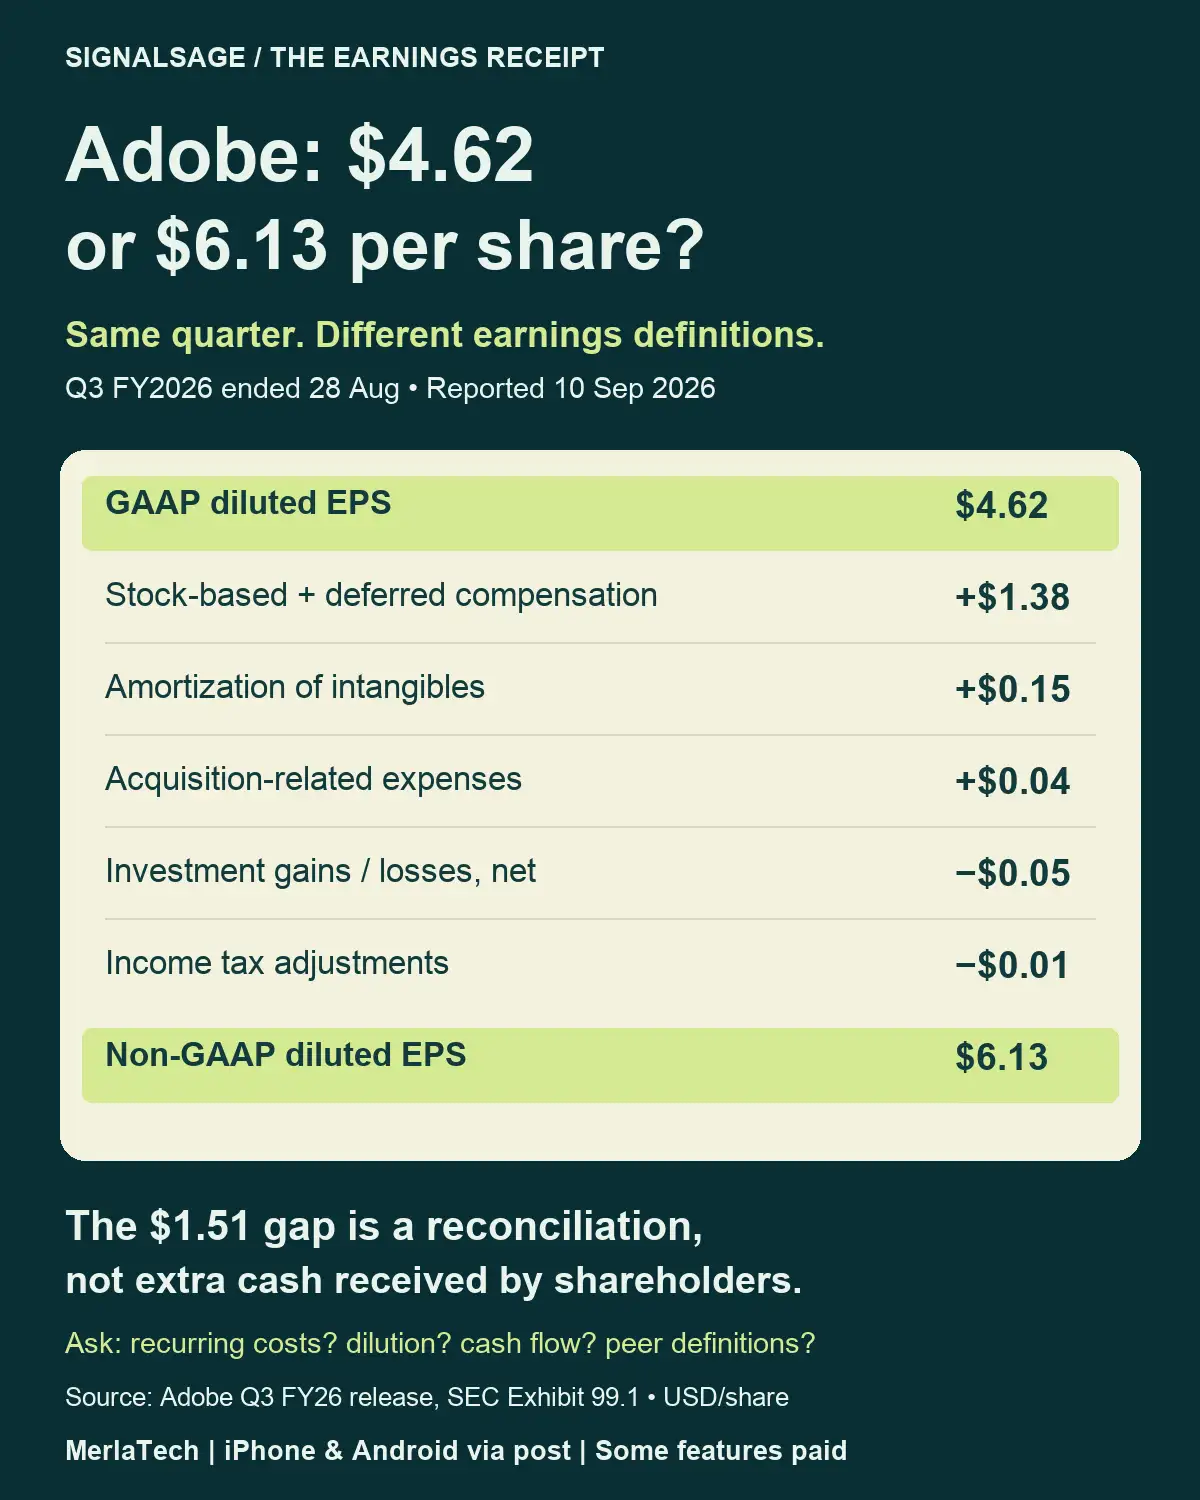
Adobe reported Q3 FY2026 diluted EPS of $4.62 under GAAP and $6.13 on its non-GAAP basis. The quarter ended 28 August; the release was dated 10 September 2026.
The per-share bridge is $4.62 + $1.38 stock-based/deferred compensation + $0.15 intangible amortization + $0.04 acquisition expenses − $0.05 investment gains/losses − $0.01 tax adjustments = $6.13. Figures are rounded as reported.
The $1.51 gap is not extra cash paid to shareholders. Ask which excluded costs recur, how equity compensation affects dilution, what the cash-flow statement shows, and whether peer definitions match. Neither EPS measure alone establishes valuation or future returns.
Source: Adobe SEC earnings release, 10 September 2026
SignalSage by the MerlaTech team — US stock research. English UI; some features require in-app purchases/subscriptions. Education, not investment advice.
iPhone & Android: iPhone and Android download page
Start with a definition before comparing a multiple. If a price-to-earnings ratio uses one company’s adjusted earnings and another company’s GAAP earnings, an apparent difference can reflect accounting choices as well as business economics. Keep the price date and earnings period consistent, then place both definitions side by side.
A charge can be noncash in the current quarter and still matter economically. Equity compensation can affect existing owners through share issuance; cash used for repurchases is a separate financing decision. A repurchase headline alone does not settle how much dilution was offset. Read weighted-average diluted shares, actual issuances and cash spending together.
For acquisition-related items, separate the company’s presentation from your forecast assumptions. A recurring acquisition strategy can produce repeated excluded costs. Intangible amortization and cash spent to buy a business occur on different schedules. Do not label an expense permanently irrelevant simply because an adjusted measure removes it.
A useful research note has four fields: the reported GAAP result; the complete company reconciliation; the cash-flow and share-count checks still needed; and the assumptions behind your comparison. Preserve the original definition even if you later build a different analytical view. Avoid combining selected adjustments from different periods to manufacture a preferred result.


Comments
Post a Comment